A useful health insurance quote starts with who needs coverage, where they live, and the care they expect to use. For individuals and families shopping on their own, a quote offers a starting estimate, not a final promise. The plans available and their costs depend on location, so one household’s result may not fit another’s. A deductible is the amount you pay for covered care subject to a deductible before your plan starts paying for those services. We can help you compare plan benefits and likely spending before you choose. Look at the doctors, medicines, and services each option covers, then weigh the costs across a full year. A low monthly price may come with more spending when you need care. Compare the amount you would pay each month with the costs you could face when you use care.
Key Takeaways
- Compare available plans for your location and household.
- Check doctors, medicines, and covered care before choosing.
- Weigh monthly premiums against costs when you use care.
- Use Marketplace enrollment to be considered for income-based savings.
- Review plan documents before you enroll.
Where Can You Buy Health Insurance on Your Own?
Most people buying their own comprehensive coverage can start at HealthCare.gov or their state’s health insurance Marketplace. These sites help individuals and families compare insurance plans available in their area. Start with the Marketplace if you may qualify for savings, because only Marketplace enrollment can unlock income-based help.
Marketplace eligibility generally requires living in the United States, being a U.S. citizen, national, or lawfully present, and not being incarcerated. Certified brokers and some insurer websites can help with Marketplace enrollment, but the application must still go through the Marketplace for savings consideration.
Only Marketplace enrollment can qualify you for income-based savings, even when an agent or insurer helps with the application.
Marketplace websites and state exchanges
HealthCare.gov directs shoppers to the right Marketplace, including a state-run exchange when one serves their area. Marketplace shoppers can apply for a premium subsidy and, if eligible, cost-sharing reductions. These savings do not apply to individual-market plans bought directly off-exchange.
State tools can make comparisons more useful than a premium list alone. For example, GetCoveredNJ’s Shop and Compare Tool shows monthly premiums, covered doctors, estimated yearly health costs, and possible financial help. That view can help us spot a plan that costs more each month but fits expected care better.
Brokers, agents, and insurer websites
Brokers often offer insurance plans from multiple companies, while agents generally work for one company. Consumers do not pay directly for their services. An insurer’s website can also show its own plans, but it may not display other companies’ options.
Direct shopping can suit people who want to check one insurer’s network or off-exchange choices. Yet an off-exchange plan cannot receive income-based Marketplace savings. Check that an application is submitted through the Marketplace if you want to be considered for income-based savings.
What Information Do You Need for Private Health Insurance Quotes?
Have your ZIP code, household details, and estimated annual income ready before you compare quotes. Accurate details matter because they help identify plans that match your location, family, and care needs. Private Health Insurance Quotes become more useful when each applicant’s doctors and prescription drugs are considered.
Enter the same household and care details each time, so the results reflect a fair comparison. Include a spouse or dependent when that person will need coverage. A quote calculator can estimate costs, but it cannot make a final subsidy decision or guarantee the final price.
Details to have ready
Quote applications may ask for several details about the people who need coverage. Gather these items before you start:
- ZIP code and county where applicants live.
- Each applicant’s date of birth and tobacco use.
- Tax household size and estimated annual household income.
- Doctors, medications, health conditions, and expected care needs.
Use the same tax household information across your comparisons. The household for an application can include people who do not all need coverage, so answer each question carefully.
Matching providers and prescriptions
List each person’s doctor, preferred hospital, regular prescriptions, and ongoing treatment needs. A health insurance plan may cover a medicine but set limits on how you can get it. Provider and drug details help narrow plans before you review full plan documents.
Shoppers looking for the best private health insurance quotes should compare how well each option fits their real care. Affordable private health insurance quotes can still leave a household with poor access to its doctors or medicines. Private health insurance quotes in California are available through Covered California.
KFF’s calculator shows estimated 2026 premiums in all states, but its results are not final prices or subsidy decisions. Enter the same household and care information for each comparison so the results are useful side by side.
How Much Does Individual Health Insurance Cost?
A monthly premium is only one part of what you may spend on a health plan. Premiums, deductibles, copays, and coinsurance all affect yearly costs. Compare the full picture, since a cheaper premium can come with higher bills when you use care.
Household size, income, age, location, coverage level, and financial help all affect health insurance costs. National Marketplace figures show the average full-price premium was $741 per month in 2026, compared with $619 in 2025. The average Marketplace premium subsidy was $650 monthly in 2026, up from $550 in 2025. Those averages are not individual quotes.
Premiums and total yearly costs
Your premium is the amount you pay each month to keep coverage. The deductible is the amount you pay for covered care subject to a deductible before the plan starts paying for those services. Copays are set fees, while coinsurance is a share of a service’s cost.
Out-of-pocket costs include deductibles, copays, and coinsurance. Some services may have different rules, so check the plan documents before estimating what care might cost. Insurers proposed a median individual-market premium increase of about 15% for 2027, before subsidies. That increase is proposed, not a final rate.
How the four metal levels compare
Marketplace insurance plans use four metal levels to show how premiums and out-of-pocket costs often balance. The levels do not measure the quality of care. Instead, they offer a simple way to compare plan cost patterns.
| Metal level | Typical monthly premium pattern | Typical out-of-pocket pattern |
|---|---|---|
| Bronze | Usually lower | Usually higher costs |
| Silver | Usually lower-to-middle | Usually moderate costs |
| Gold | Usually higher | Usually lower costs |
| Platinum | Usually highest | Usually lowest costs |
Compare estimated yearly premiums plus likely out-of-pocket costs, not the monthly price alone.
How Can Marketplace Savings Lower Your Premium?
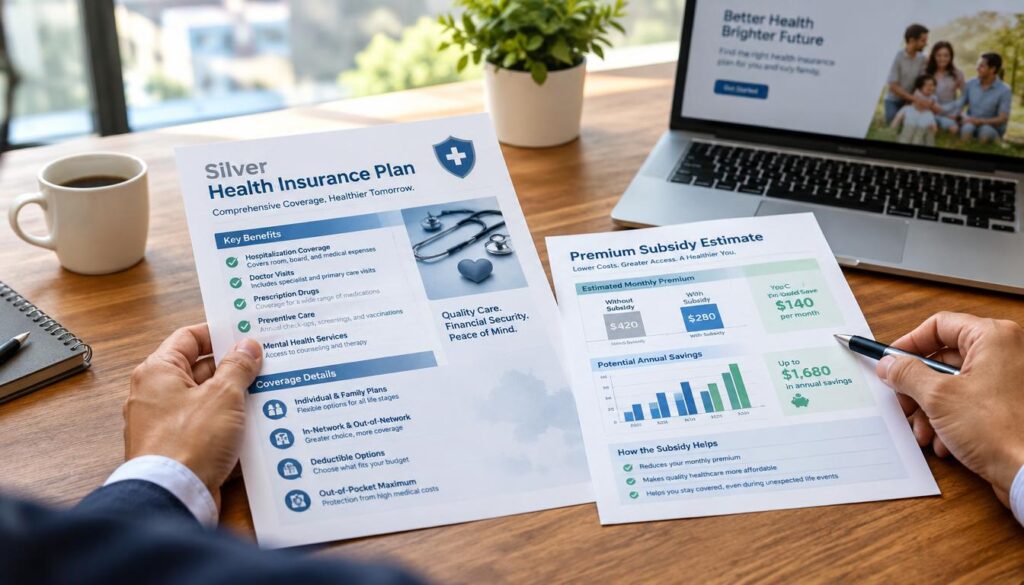
Marketplace financial help can lower premiums, and some eligible Silver plan buyers can also reduce costs when they use care. The two kinds of help work differently: a premium subsidy lowers monthly premiums, while cost-sharing reductions lower certain bills for covered care.
Final eligibility comes from the Marketplace application, not a calculator estimate. Household income, household size, and location affect who may qualify and how much help they receive. Alaska and Hawaii use higher federal poverty levels than the continental states.
Premium tax credits
For 2026 coverage, premium tax credits generally apply to Marketplace buyers with household incomes from 100% to 400% of the federal poverty level. KFF’s calculator uses a 2026 level of $15,650 for one person and $32,150 for a family of four in most states.
For a benchmark Silver plan in 2026, the expected contribution ranges from 2.1% to 9.96% of household income. KFF’s 2026 calculator can estimate premiums, but the Marketplace decides eligibility after reviewing an application. During 2026 open enrollment, 87% of enrollees qualified for premium subsidies.
Cost-sharing reductions
Cost-sharing reductions can lower deductibles, copays, and coinsurance for eligible people with incomes from 100% to 250% of the federal poverty level. These savings require enrollment in a Silver plan. They are separate from premium tax credits, and one type of help does not replace the other.
For 2027 coverage, the expected income contribution for subsidized benchmark Marketplace coverage ranges from 2.15% to 10.22%. In the continental United States, a single person may qualify with income up to $63,840; a household of four has a stated threshold of $132,000.
Update your income estimate if it changes so your Marketplace savings reflect your current circumstances.
Which Type of Health Insurance Fits Your Needs?
For comprehensive individual or family coverage, an ACA Marketplace plan is the clearest starting point. ACA Marketplace major-medical plans are a common private option, though plans available vary by location. They offer broad benefits, including care that limited policies may leave out.
Marketplace plans cover 10 essential health benefits, pre-existing conditions, and in-network preventive services at no cost. Benefits include prescription drugs, emergency services, hospitalization, lab services, and mental health and substance use disorder services.
Marketplace plans for comprehensive coverage
Marketplace health plans must cover the 10 essential health benefits. They also cover pre-existing conditions, and in-network preventive care is free. These protections make them a strong fit for people who need ongoing care or want broad medical coverage.
Medicaid and CHIP are public coverage programs, not private medical plans. Eligible people can enroll in them year-round. Dental and vision coverage may be available as supplemental policies, but those policies do not replace comprehensive medical coverage.
Short-term plans for temporary gaps
Short-term health insurance may help fill a temporary gap, but it is not an ACA-compliant substitute. It has no specific essential-health-benefit coverage requirements, so covered services vary by plan. Most UnitedHealthcare short-term plans are medically underwritten and do not cover pre-existing conditions.
| Feature | Marketplace plan | Short-term plan |
|---|---|---|
| Coverage standards | 10 essential health benefits | No specific essential-health-benefit requirements |
| Pre-existing conditions | Covered | Generally excluded by most UnitedHealthcare short-term plans |
| Duration | Full calendar year while premiums are paid | UnitedHealthcare: 1 month to nearly 12 months; TriTerm: up to 3 years in some states |
UnitedHealthcare short-term medical plan length depends on state and plan. TriTerm Medical can last up to three years in some states. Read the plan documents closely before choosing a limited short-term policy.
How Do You Compare Plans for Doctors, Drugs, and Total Costs?
The best plan for most shoppers is the one that covers their needed care and providers at a total cost they can manage. An ACA Marketplace plan is a strong choice for comprehensive coverage when its doctors and prescriptions fit. Choose by actual needs, not by a plan name alone.
No health plan covers literally everything, and essential benefits can still have limits. A Silver plan may suit someone eligible for cost-sharing reductions. A lower-premium Bronze plan may fit someone focused on monthly cost who can handle higher costs when using care.
Use this checklist to compare the details that affect access and spending:
- Confirm your doctors and hospitals are in network.
- Search the drug formulary and check coverage rules.
- Compare deductibles, copays, and coinsurance.
- Review exclusions and service limits in plan documents.
For 2026, the maximum annual out-of-pocket limit for Marketplace coverage is $10,600 for an individual and $21,200 for a family. Check the 2026 out-of-pocket limit as a ceiling for covered cost sharing, not as a promise that all care is covered.
When Can You Enroll in a Health Insurance Plan?
In most states, the next Marketplace open enrollment window for 2027 coverage runs from November 1 through January 15. Enrollment dates matter: they set when coverage can begin and when most shoppers can select a plan.
Eligible people generally have at least 60 days after a qualifying life event to choose a plan. Outside open enrollment, a qualifying life event may open a Special Enrollment Period for enrollment or plan changes. Eligible people can enroll in Medicaid or CHIP at any time of year.
Outside open enrollment, a qualifying life event generally opens a limited time to choose or change Marketplace coverage.
Use this three-step enrollment checklist:
- Note the November 1 to January 15 window for 2027 coverage in most states.
- Enroll by December 15 for January 1 coverage, or by January 15 for February 1 coverage.
- Outside the window, check for a qualifying event; eligible Medicaid and CHIP applicants can enroll year-round.
During 2026 open enrollment, 23.1 million people selected Marketplace plans nationwide, down from 24.3 million the year before. Individual-market enrollment fell from 25.2 million in June 2025 to 20.5 million in June 2026, an 18% drop. These totals do not decide any one person’s eligibility or local plan choices.
HealthCare.gov’s Marketplace enrollment guide lists the federal dates and coverage start times. Confirm your state’s deadline and coverage start date before submitting an application.
Conclusion
A confident choice starts with a clear picture of the care your household needs and the costs you can afford. We can make a better choice when we compare providers, prescriptions, and expected spending alongside benefits.
Gather details for everyone who needs coverage, including income estimates and regular care needs. Compare the plans available through the Marketplace, then read each plan’s documents for limits and exclusions. A quote can point us toward options, but the full policy shows how coverage works when care is needed.
Gather your household details and compare available plans through your state or federal Marketplace.